
Einar H. Dyvik
Research expert covering Nordics and global data for society, economy, and politics
At 30.77 trillion U.S. dollars, U.S. nominal GDP crossed the 30-trillion threshold for the first time in 2025, yet the headline figure conceals a more cautious underlying story. Real annual GDP growth slowed to 2.1 percent in 2025, down from 2.8 percent in 2024, pointing to an economy that had largely absorbed its post-pandemic rebound before a new headwind emerged. The Trump administration's broad tariff program introduced additional pressure: estimates put the permanent long-run impact of tariffs on GDP at a 0.5 percent reduction, rising to 0.7 percent if trading partners respond with reciprocal measures.
The deceleration at the aggregate level did not translate into stagnation for households. Real GDP per capita rose to 69,749 chained 2017 U.S. dollars in 2025, extending an unbroken run of annual per-person gains since 2021. The contrast with 2020, when the figure fell sharply to 61,127 chained 2017 U.S. dollars, illustrates how quickly the labor market tightened after the pandemic shock and how durably that tightening supported real living standards even as growth moderated at the macro level.
The composition of U.S. output reinforces a long-established structural pattern. Finance, insurance, real estate, rental, and leasing contributed 6,680.4 billion U.S. dollars to value added by industry in 2025, more than twice the 2,896.5 billion U.S. dollars contributed by U.S. manufacturing. That gap matters for policy: an economy so heavily weighted toward asset-intensive and knowledge-intensive services is more sensitive to interest rate conditions and financial market sentiment than to shifts in goods production capacity.
Growth in 2025 was not evenly distributed. Florida and South Carolina each expanded at 3.1 percent, the fastest pace among all states, according to state real GDP growth rates. Even California and Texas, which together account for the largest share of national output, expanded at 2.5 percent, above the national rate, suggesting the drag came largely from slower-growing commodity and agricultural states such as North Dakota, which posted just 0.3 percent. This divergence points to a structural reallocation of activity toward migration-destination markets rather than a broad-based slowdown.
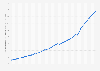
U.S. GDP forecasts project nominal output rising from 31,902 billion U.S. dollars in 2026 to 46,712 billion U.S. dollars by 2036, an addition of roughly 16 trillion U.S. dollars over eleven years. The consistency of year-on-year growth across the forecast window reflects an expectation of stable conditions rather than acceleration, which aligns with the 2025 data: a large, mature economy capable of steady compounding but unlikely to return to the above-trend rates that briefly followed the pandemic reopening. Should tariff-driven trade disruptions prove more persistent than current projections assume, even that measured path could come under pressure.

Detailed statistics
Real GDP growth rate in the U.S. 1990-2025

Detailed statistics
Gross domestic product (GDP) per capita in the United States 1980-2031
Detailed statistics
Gross domestic product (GDP) in current prices in the United States 1980-2031